The Ins and Outs of Loans: Browsing Your Funding Selections With Confidence
Maneuvering the complex landscape of loans calls for a clear understanding of various types and necessary terms. Many individuals discover themselves overwhelmed by options such as individual, automobile, and pupil loans, along with vital concepts like rate of interest and APR. An understanding of these fundamentals not just help in reviewing economic needs however additionally boosts the loan application experience. There are significant aspects and common risks that customers should identify before continuing additionally.
Understanding Various Kinds Of Loans
Loans serve as vital financial devices that deal with various demands and goals. Individuals and businesses can select from several sorts of loans, each created to satisfy details needs. Personal loans, usually unsafe, give borrowers with funds for various individual costs, while vehicle loans enable the purchase of automobiles through safeguarded financing.
Home mortgage, or home mortgages, assist customers in acquiring home, normally involving lengthy repayment terms and particular rate of interest. Student loans, focused on moneying education and learning, often come with reduced interest prices and credit alternatives till after graduation.
For organizations, business loans supply needed capital for development, devices acquisitions, or functional costs. Furthermore, copyright loans offer quick cash options for immediate needs, albeit with greater rate of interest. Understanding the various sorts of loans enables customers to make informed choices that align with their financial goals and circumstances.
Trick Terms and Ideas You Ought To Know
Recognizing crucial terms and principles is necessary when maneuvering loans. Rate of interest play a crucial function in establishing the cost of borrowing, while different loan types satisfy various monetary requirements. Experience with these aspects can empower individuals to make educated decisions.
Interest Rates Clarified
Just how do rate of interest effect borrowing decisions? Rates of interest stand for the expense of borrowing cash and are an essential consider financial decision-making. A higher passion rate enhances the total cost of a loan, making loaning less attractive, while reduced rates can incentivize customers to take on financial obligation. Lenders use interest prices to reduce risk, reflecting borrowers' credit reliability and prevailing financial problems - Payday Loans. Fixed rate of interest remain consistent throughout the loan term, supplying predictability, whereas variable rates can fluctuate, possibly causing higher payments with time. Furthermore, recognizing the interest rate (APR) is crucial, as it includes not simply interest but also any type of associated charges, giving a comprehensive view of loaning costs
Loan Enters Review
Maneuvering the landscape of loan kinds is vital for consumers looking for one of the most suitable financing choices. Understanding different loan types helps individuals make educated choices. Individual loans are normally unsecured, suitable for consolidating debt or funding individual tasks. Mortgages, on the other hand, are secured loans particularly for buying property. Auto loans offer a comparable purpose, funding lorry purchases with the lorry as security. Business loans satisfy entrepreneurs requiring capital for operations or growth. An additional alternative, trainee loans, aid in covering academic costs, often with desirable repayment terms. Each loan type provides unique terms, passion prices, and eligibility requirements, making it necessary for consumers to analyze their financial demands and capacities prior to dedicating.
The Loan Application Refine Discussed
What actions must one require to efficiently browse the loan application procedure? Initially, individuals ought to evaluate their monetary needs and figure out the kind of loan that aligns with those needs. Next, they need to evaluate their credit score record to confirm accuracy and identify areas for enhancement, as this can affect loan terms.
Following this, borrowers must gather required documentation, consisting of proof of revenue, employment history, and economic statements. As soon as prepared, they can come close to loan providers to ask about loan items and rate of interest.
After picking a lender, completing the application properly is crucial, as omissions or mistakes can postpone processing.
Lastly, applicants should await potential follow-up demands from the lender, such as extra documentation or clarification. By following these actions, people can boost their chances of a efficient and smooth loan application experience.
Factors That Influence Your Loan Approval
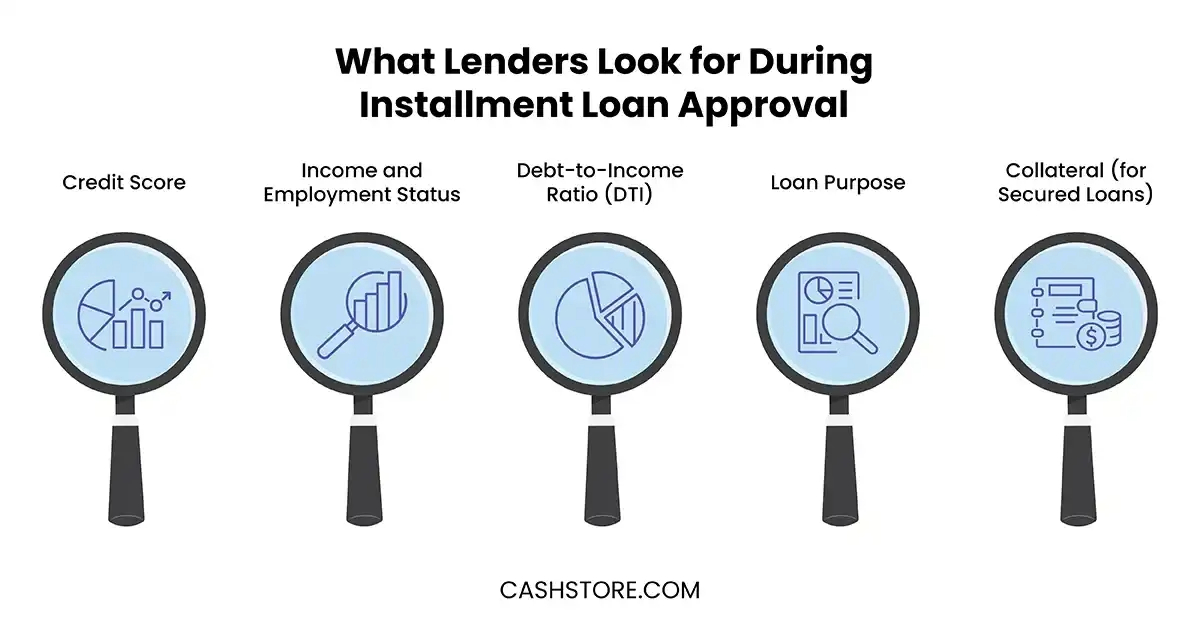
When taking into consideration loan approval, a number of essential aspects enter into play. Two of one of the most substantial are the credit history here score and the debt-to-income ratio, both of which supply lenders with insight right into the consumer's monetary security. Recognizing these elements can greatly boost a candidate's chances of protecting the preferred financing.
Credit Score Value
A credit score offers as a vital criteria in the loan authorization process, influencing loan providers' assumptions of a consumer's financial dependability. Commonly ranging from 300 to 850, a higher score suggests a background of accountable credit scores usage, including timely repayments and low credit score utilization. Different factors contribute to this rating, such as repayment history, length of credit report, sorts of charge account, and current debt questions. Lenders make use of these ratings to assess threat, establishing loan terms, rate of interest, and the likelihood of default. A strong credit rating not just boosts approval possibilities yet can additionally result in much more beneficial loan problems. Conversely, a low rating might result in greater passion prices or rejection of the loan application altogether.
Debt-to-Income Proportion
Lots of lenders consider the debt-to-income (DTI) proportion a crucial aspect of the loan authorization process. This financial statistics compares a person's regular monthly debt payments to their gross month-to-month earnings, providing understanding into their ability to take care of extra financial debt. A lower DTI proportion suggests a healthier monetary scenario, making consumers extra attractive to lenders. Variables influencing the DTI ratio consist of housing expenses, credit scores card balances, pupil loans, and other persisting expenses. Furthermore, modifications in income, such as promos or work loss, can considerably influence DTI. Lenders commonly favor a DTI ratio below 43%, although this limit can differ. Taking care of and understanding one's DTI can improve the opportunities of securing favorable loan terms and rates of interest.
Tips for Handling Your Loan Responsibly

Common Mistakes to Prevent When Taking Out a Loan
Additionally, many people hurry to accept the very first loan deal without contrasting options. This can result in missed out on possibilities for much better terms or lower prices. Customers ought to likewise stay clear of taking on loans for unnecessary expenses, as this can result in long-lasting financial debt troubles. Ignoring to analyze their credit scores score can impede their capability to protect favorable loan terms. By recognizing these risks, debtors can make educated choices and browse the loan process with greater confidence.
Frequently Asked Questions
Just How Can I Improve My Credit Score Before Obtaining a Loan?
To improve a credit score prior to making an application for a loan, one must pay expenses promptly, lower arrearages, examine credit rating reports for errors, and avoid opening up brand-new charge account. Constant monetary routines yield positive outcomes.
What Should I Do if My Loan Application Is Rejected?
Exist Any Costs Connected With Loan Prepayment?
Financing early repayment costs might use, depending on the lender and loan type. Some loans include penalties for very early payment, while others do not. It is vital for debtors to examine their loan contract for certain terms.
Can I Work Out Loan Terms With My Loan provider?
Yes, debtors can discuss loan terms with their loan providers. Aspects like credit report, repayment history, and market problems may influence the lender's determination to customize rate of interest rates, repayment routines, or costs connected with the loan.
Just How Do Rate Of Interest Affect My Loan Settlements Gradually?
Rates of interest considerably influence loan payments. Higher prices lead to increased monthly settlements and overall interest costs, whereas lower prices lower these expenditures, eventually impacting the borrower's overall economic worry throughout the loan's duration.
Several people locate themselves bewildered by alternatives such as individual, auto, and trainee loans, as well as crucial ideas like interest rates and APR. Rate of interest prices play an essential role in figuring out the price of loaning, while different loan types provide to different economic requirements. A higher passion price enhances the total price of a loan, making borrowing much less enticing, while lower prices can incentivize debtors to take on financial debt. Dealt with interest prices remain consistent throughout the loan term, offering predictability, whereas variable rates can change, possibly leading to greater payments over time. Loan prepayment charges may apply, depending on the lender and loan type.
Comments on “Money Management Tips: How to Use a copyright Without Overpaying”